Storm damage and insurance
Storm damage and insurance: what we do and don't do.
After a storm, we'll inspect your roof for free and show you exactly what's there, with dated photos you keep. We can also meet your insurance adjuster to review what we found.
The claim itself is between you and your insurance company. We don't handle, negotiate or manage claims, and Texas law doesn't allow a roofer to act as your public adjuster.
What we do.
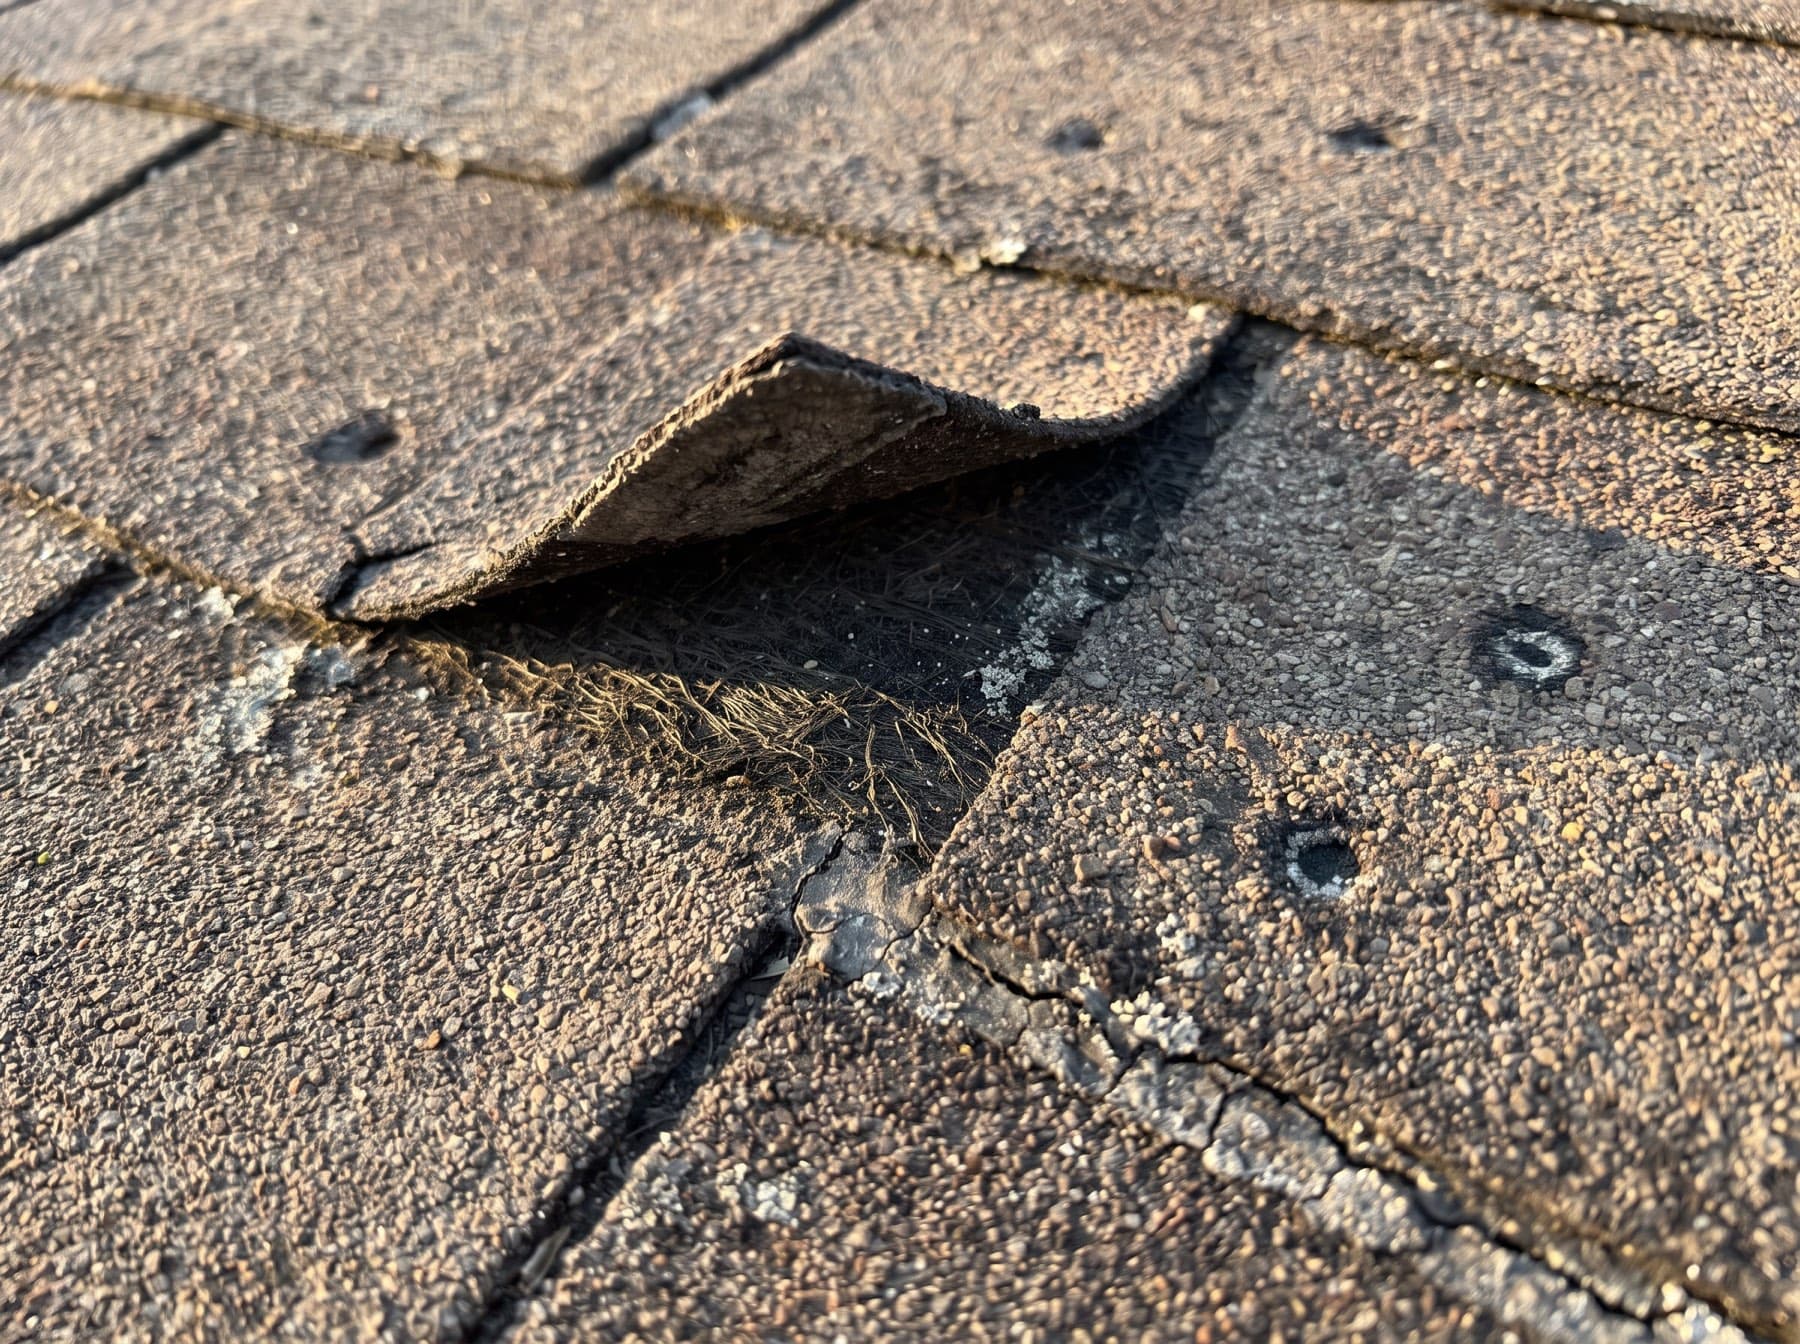
We document damage with dated photos.
Each photo shows where and when it was taken. If we don't find any storm damage, we'll tell you that too, and show you the photos.
We can meet your adjuster to review our findings.
If your insurance company sends an adjuster, we can be there to walk through what we photographed. Our job is to show what's on the roof.
We refer coverage disputes to independent professionals.
If you need help with a coverage dispute, we'll refer you to an independent licensed public adjuster or attorney. We don't take that role ourselves.
We give you options if your insurance doesn't cover it.
If a repair or replacement isn't covered, we'll give you a locked price in writing and our published decking rate. There's no pressure to decide.
What we don't do.
- We don't act on your behalf with your insurance company, and we don't interpret your policy.
- We don't tell you what your claim is worth, and we don't promise any outcome.
- We don't pay, waive, absorb or rebate your deductible, and we never offer to.
- We don't ask you to sign anything on the day of the inspection.
What Texas law says
Your deductible has to be paid.
Texas law requires you to pay your insurance deductible. It prohibits roofing contractors from waiving, absorbing or rebating it, and from advertising that they will (Texas Business & Commerce Code §27.02).
Texas law also says a roofing contractor can't act as your public adjuster or advertise that it will handle your claim (Texas Insurance Code §4102.163). That's why we refer coverage disputes to independent licensed professionals.
If a roofer offers to “take care of” your deductible or “fight” your insurer, we'd recommend finding a different roofer.
High deductible? See the numbers first.
Book a free storm inspection.
Common questions.
Can't find your answer? Call us at (713) 909-0443.
How do I know if my roof damage is covered?
Only your insurance company can decide that, based on your policy. What we can do is inspect the roof and give you dated photos of what's there, including when we don't find storm damage.
If you have questions about your policy or a coverage dispute, talk to your insurance agent, or an independent licensed public adjuster or attorney.
Should I file a claim?
That's your decision, and we won't tell you whether to file. Many Texas wind and hail deductibles are a percentage of the home's insured value, so it's worth checking your deductible with your agent first. Our instant price can show you the cost of paying cash next to your deductible.
Will you meet my adjuster?
Yes, if you'd like us to. We walk through what we photographed and answer questions about the roof's condition. We don't negotiate with your insurer or act on your behalf.
Can you cover my deductible?
No. Texas law requires you to pay your deductible and prohibits roofers from waiving, absorbing or rebating it. If a roofer offers to, they're offering to break the law. Monthly payments are available through our lending partner, subject to credit approval.